

Waiting for Mortgage Rates to Drop? Here's What History Can Teach Today's Homebuyers
If you've been thinking about buying a home but keep putting it off because of mortgage interest rates, you're not alone. Many buyers are watching the market, hoping rates will come down before they make their move.
And honestly, that's understandable. Interest rates affect your monthly payment, your buying power, and the overall cost of owning a home.
But here's something worth considering: Today's mortgage rates may feel high compared with recent years, but history tells a much bigger story.
Mortgage Rates Haven't Always Been This Low
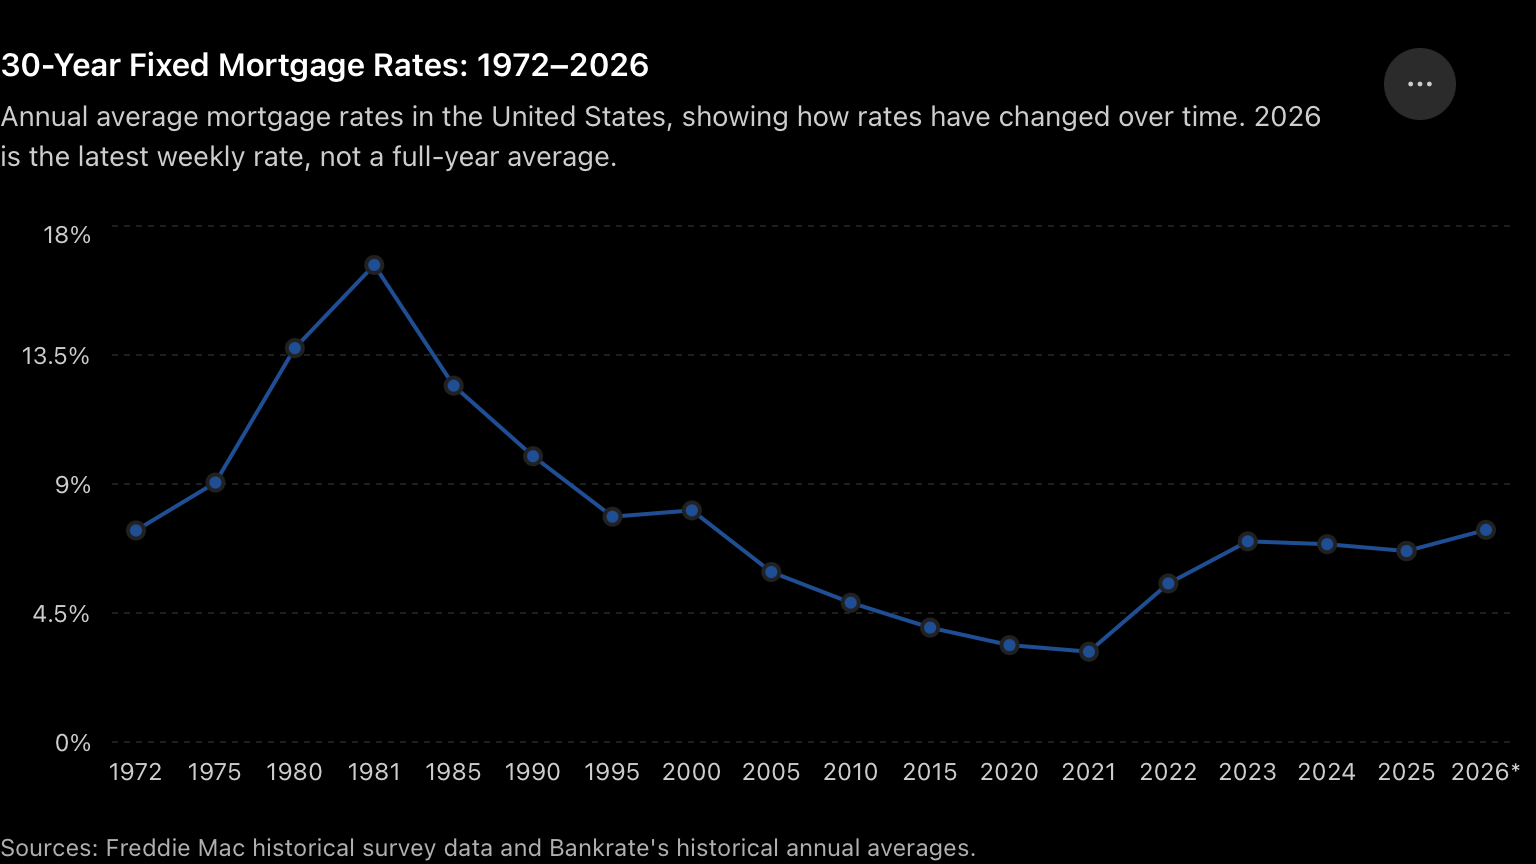
During the early 1980s, mortgage interest rates climbed above 16% on an annual-average basis. In 1981, the average rate for a 30-year fixed mortgage reached 16.64%. Throughout much of the 1990s, rates were still considerably higher than the rates many buyers became accustomed to during the past decade.
Then came the historically low rates of 2020 and 2021, when average 30-year mortgage rates fell to around 3%.
Those rates were wonderful for buyers who were able to take advantage of them. But they also created a new expectation that mortgage rates in the 3% range were normal.
They weren't. They were unusually low by historical standards.
As rates moved higher in the years that followed, many buyers began to feel that homeownership was suddenly out of reach. But understanding the history of mortgage rates can help us look at today's market with a little more perspective.
 Should You Wait for Interest Rates to Drop?
There's no way to know exactly where mortgage rates will go next. They may rise, fall, or fluctuate over time. Waiting for a lower rate could pay off, but it could also mean spending more time renting or missing a home that would have been a good fit.
And interest rates are only one part of the equation.
The home's purchase price, your down payment, credit score, property taxes, homeowners insurance, and other expenses all affect what you can comfortably afford.
Depending on your circumstances, you may find that buying now makes sense. Or you may discover that a little more preparation will put you in a better position to buy later. Either way, getting accurate information is more useful than making a decision based on headlines alone.
You Don't Have to Figure It Out Alone
If buying a home is on your mind, consider taking a few simple steps:
Talk with a mortgage lender. Find out what you may qualify for and request an estimate of your monthly payment.
Explore different price ranges. You may have more options than you realize.
Ask about available loan programs. Depending on eligibility, certain programs may offer lower down payment requirements or other assistance.
Look at the complete monthly cost. Remember to include taxes, insurance, maintenance, and any applicable mortgage insurance.
Keep your future in mind. Think about how long you plan to stay in the home and whether the payment fits your budget comfortably.
The Right Time to Buy Is Personal
Buying a home is a major financial decision, and there is no single answer that works for everyone. No one should feel pressured to buy before they're financially ready.
But if you've been assuming homeownership is impossible simply because interest rates aren't where you'd like them to be, it may be worth taking another look.
You don't have to predict the market perfectly. You just need to understand your options and make an informed decision based on your own circumstances.
At Phillips Realty Group, we're here to help you explore homes throughout Jackson and West Tennessee, understand your options, and take the next step when you're ready.
Curious about what you could buy in today's market? Visit phillipsrg.com to start exploring available homes, or reach out to our team. A conversation today could help you plan for homeownership tomorrow.
Phillips Realty Group | Helping you find your place in West Tennessee.
Check out this article next